
25 Aug 2026
Are Your Related Party Transactions UAE Corporate Tax Compliant?
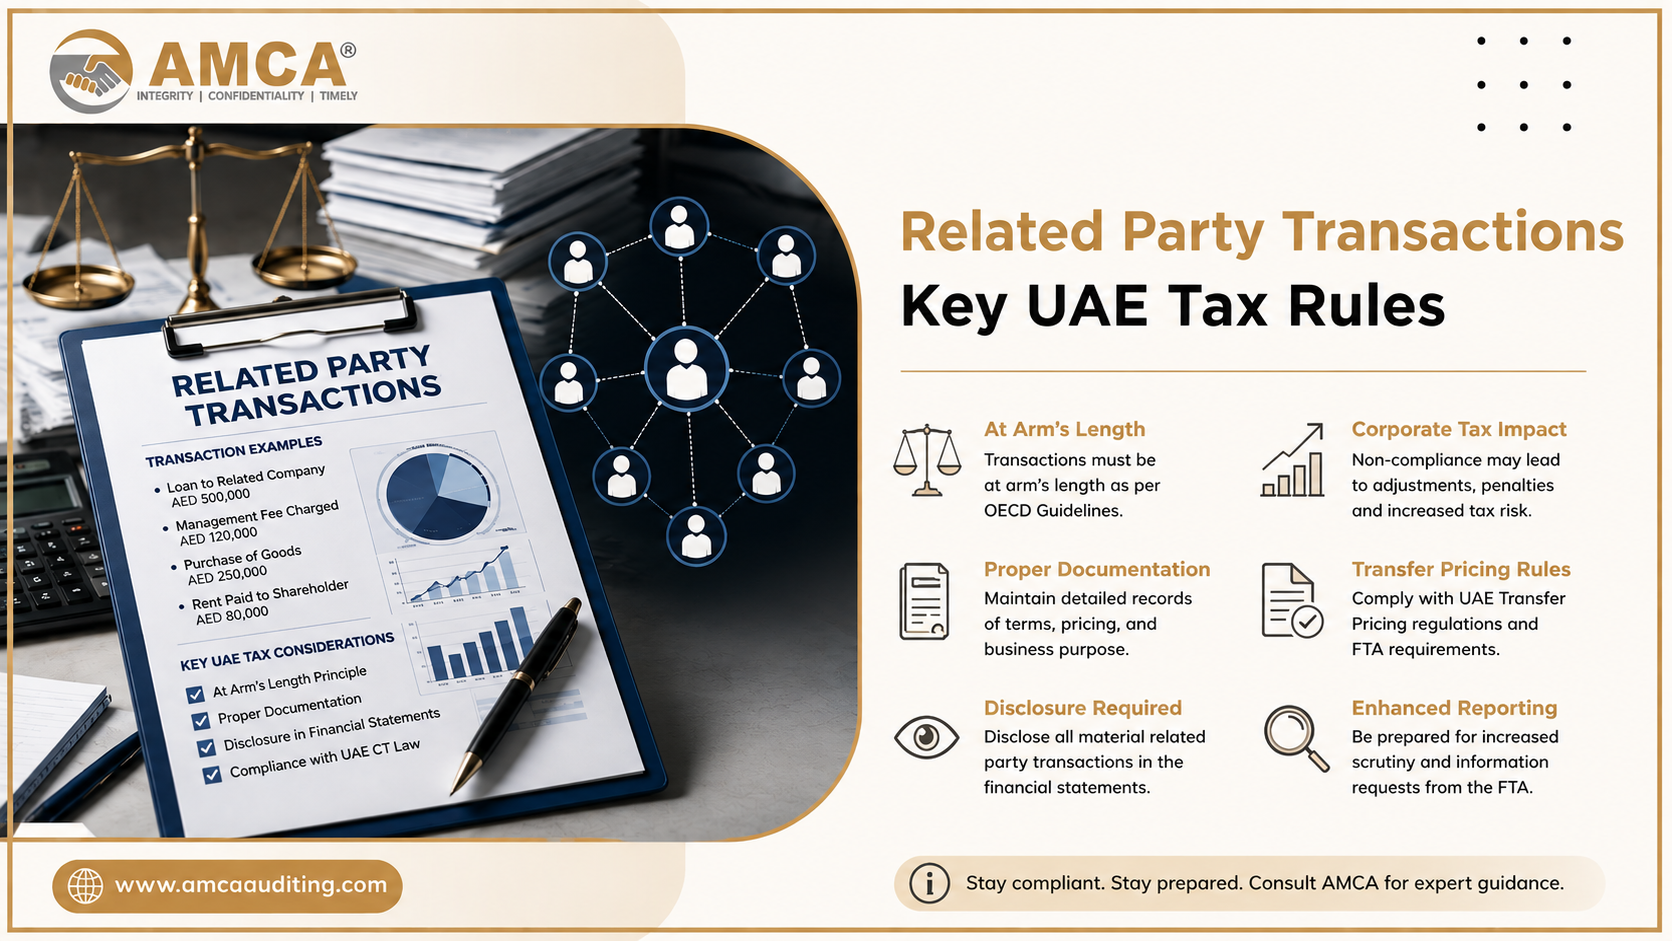
With the introduction of UAE Corporate Tax, businesses must carefully review transactions with related parties to ensure they meet tax compliance requirements. Payments, benefits, and arrangements between connected entities must reflect genuine business purposes and follow the Arm’s Length Principle to avoid tax risks.
What Are Related Party Transactions Under UAE Corporate Tax?
Related Party Transactions include arrangements between entities or individuals that meet the UAE Corporate Tax Law tests for ownership, control, kinship, partnership, or other specified relationships. Under Federal Decree-Law No. 47 of 2022, related parties may include companies under common ownership, controlling shareholders, partners, certain relatives, and connected persons where the statutory conditions are met.
Common examples include:
- Management fees charged between group companies
- Loans or financial arrangements between related entities
- Transfer of goods or services between connected businesses
- Payments made to shareholders, directors, or their related parties
Why Do Businesses Need to Review These Transactions?
The UAE Corporate Tax Law requires related party transactions to follow market-based pricing. Businesses must ensure that transactions are conducted as they would be between independent parties.
Under Article 34 of Federal Decree-Law No. 47 of 2022, the Arm’s Length Principle applies to related party transactions, ensuring that income and expenses are determined based on fair market conditions.
Additionally, Article 36 states that payments or benefits provided to connected persons are deductible only when they match market value and are incurred wholly and exclusively for taxable person’s business.
How Can Businesses Stay Prepared?
To maintain compliance, businesses should:
-
Identify all related party transactions
- Maintain proper agreements and supporting documentation
- Review pricing policies against market conditions
- Prepare transfer pricing documentation where applicable
- Ensure accurate reporting in Corporate Tax filings
Businesses should also assess whether statutory transfer pricing documentation requirements apply, including the need to maintain a master file, local file, and disclosure form where the relevant conditions and thresholds are met.
Early review helps businesses reduce compliance risks and remain prepared for potential FTA reviews.
Need Support With UAE Corporate Tax Compliance?
AMCA Auditing helps businesses review related party transactions, assess transfer pricing requirements, and strengthen Corporate Tax compliance processes.
Get expert guidance today
.jpg "FTA Decision No. 9 of 2025 – New VAT Refund Rules in the UAE")
.jpg "How Professional Accounting Helps Businesses Grow Faster")
.jpg "How Professional Accounting Helps Businesses Grow Faster")
.jpg "Company Liquidation Delays in UAE: The Top 7 Reasons Authorities Reject Applications")